
In this article, I’ll be discussing the Top Petal Card Competitors for US Cash Flow Underwriting, and how leading financial companies assess applicants based on banking data, income patterns, and alternative credit assessment techniques.
We’ll compare target customers, underwriting approaches, credit limits, repayment structures, rewards and benefits to understand how they support credit accessibility across the US lending market.
How We Find Top Petal Card Competitors for US Cash Flow Underwriting
Cash Flow Underwriting: Look for competitors that assess creditworthiness by analyzing income, bank balances and transaction history.
Alternative Credit Assessment: Locate firms that evaluate candidates using methods other than standard credit scores and credit histories.
Target Customer Segment: Concentrate on products for thin-file, credit-building, underserved US consumers.
Data Connectivity: Assess how competitors obtain banking data via account linking and financial data.
Credit Accessibility: Compare approval requirements, eligibility criteria and accessibility for applicants with limited credit history. 6. Credit Limits: Evaluate how providers determine initial credit limits and adjust them based on financial behavior.
Repayment Flexibility: Look at repayment schedules, auto-pay, secured balances, and installment options.
Rewards and Benefits: Examine cashback, special promotions, financial tools and credit-building benefits.
Key Points & Top Petal Card Competitors for US Cash Flow Underwriting
| Competitor | Description |
|---|---|
| Arro Card | Arro Card builds credit through responsible spending, payments, and personalized financial insights. |
| Mission Lane | Mission Lane offers credit cards designed for consumers rebuilding or establishing credit. |
| Chime Card | Chime Credit Builder helps users build payment history with flexible, secured spending. |
| Varo Believe | Varo Believe offers secured credit-building features without requiring credit checks or interest. |
| PayPal Credit Products | PayPal offers revolving credit and installment products integrated into its checkout ecosystem. |
| Chase Freedom Rise | Chase Freedom Rise targets credit newcomers with rewards, reporting, and relationship-based considerations. |
| Upgrade OneCard | Upgrade OneCard combines revolving credit access with installment-style repayment and cash-back rewards. |
| Mine | Mine emphasizes accessible credit products and financial tools for underserved US consumers. |
| Deserve | Deserve provides credit cards for students, newcomers, and people with limited credit histories. |
| Capital One Quicksilver Secured | Capital One Quicksilver Secured offers credit-building access, cash-back rewards, and payment reporting. |
10 Top Petal Card Competitors for US Cash Flow Underwriting
1. Arro Card
Target Customers: Arro Card targets US consumers with limited, poor or no credit history. Data Used It looks at connected bank account data such as income, account balances, and transaction history, as well as pertinent credit factors.
Credit Limit – Users can start with around $50 – $300 and have an opportunity to increase their credit limit up to $2,500 through app-based financial activities. Repayment Structure It is based on the credit card monthly billing cycle and requires customers to make payments
As per their statement and due dates. Rewards and Benefits: 1% cash back on eligible gas and grocery purchases, financial education, credit reporting, no security deposit and soft-inquiry applications.
Rewards
- Offers cashback on eligible purchases.
- Provides rewards through its card program.
- Offers opportunities to increase rewards through card usage.
- Rewards are subject to applicable card terms.
Benefits
- Uses banking information to support credit decisions.
- Helps consumers with limited credit history access credit.
- Reports payment activity to credit bureaus.
- Provides financial education and credit-building opportunities.
2. Mission Lane
Mission Lane is here for US consumers needing access to credit, who have fair, limited, or damaged credit histories and want to build credit. Data Used: It uses its proprietary underwriting to examine credit profiles, bank account history, income and other applicant data.
Credit Limit Advertized starting limits are $1,000 for secured, $2,000 for Green Line and $3,000 for selected products depending on the card. Payment Structure: Customers pay monthly based on billing statements, with options for minimum payment and auto-payment.
Rewards & Benefits: Some cards earn 1.5% unlimited cash back or 3% on eligible gas, travel and dining, plus credit bureau reporting, digital account management and no annual fee on advertized products.
Rewards
- Selected cards offer cashback on eligible purchases.
- Some cards provide higher rewards in specific spending categories.
- Certain products offer flat-rate cashback.
- Rewards vary according to the selected card.
Benefits
- Offers unsecured and secured credit card options.
- Provides prequalification with no initial hard credit inquiry.
- Reports payment activity to major credit bureaus.
- Helps consumers build or rebuild their credit history.
3. Chime Card
Chime targets U.S. consumers who want spending and credit-building opportunities tied to their bank accounts, particularly those with limited credit histories. Data Used: Its secured structure uses deposited funds, available balances and card transaction information as opposed to relying on publicly documented unsecured cash-flow underwriting.
Credit Limit Not a standard pre-set unsecured credit line. Your available spending is determined by eligible deposited funds. Repayment Structure: The legacy Credit Builder product utilizes secured deposits to secure spending and repayment.
Rewards and Benefits: Key benefits include credit bureau reporting, no annual fee, no interest on the legacy secured product and integrated banking and mobile account management. You can’t buy new legacy Credit Builder accounts.
Rewards
- Offers eligible members access to cashback opportunities.
- Provides rewards through participating merchant offers.
- Rewards depend on account eligibility and available promotions.
- Cashback availability varies by Chime product.
Benefits
- Helps users build credit through secured spending.
- No interest charges on Credit Builder purchases.
- No annual fee for the Credit Builder card.
- Reports payment activity to major credit bureaus.
4. Varo Believe
Varo Believe targets U.S. consumers who want to build or rebuild credit through accessible, banking-linked secured spending. Data Used: Its approach focuses on eligible Varo banking relationships, secured account funding, available balances and transaction information rather than publicly established unsecured cash flow scoring.
Credit Limit: Spending power is linked to the amount of secured funds on deposit, rather than to a revolving line of credit that is set independently. Repayment Structure: It has a Safe Pay feature that will automatically pay eligible statement balances from the secured account
if sufficient funds are available. Rewards and Benefits Some of the key benefits include: No annual fee, no interest, no traditional credit check to apply and credit bureau reporting, integrated banking and spending management.
Rewards
- Provides access to selected promotional offers.
- Rewards availability depends on current Varo promotions.
- Does not primarily compete through cashback rewards.
- Focuses more on credit-building than purchase incentives.
Benefits
- Helps customers establish or improve credit history.
- Uses secured funds to support card spending.
- Safe Pay helps prevent unpaid balances.
- Reports payment activity to major credit bureaus.
5. PayPal Credit Products
PayPal Credit Products are for digital payment users, frequent online shoppers and consumers who want flexible purchase financing. Data Used: Eligibility assessment uses application information and creditworthiness checks, while PayPal’s digital ecosystem offers transaction and account activity.
Detailed cashflow underwriting variables are not public. Credit Limit: Under PayPal Credit agreements, your minimum initial credit limit will be $250. Specific limits are determined during the approval process.
Repayment Terms Customers will make monthly minimum payments and purchases of $149 or more will qualify for six-month promotional financing. Benefits and Rewards Key benefits include digital checkout, Mastercard acceptance for eligible cardholders, reusable credit access and promotional financing options.
Rewards
- Provides promotional financing on qualifying purchases.
- Offers special financing for eligible purchases.
- Supports convenient payments across participating merchants.
- Promotional offers depend on product and purchase eligibility.
Benefits
- Integrates credit options into PayPal checkout.
- Provides flexible purchasing and payment options.
- Offers digital access to credit products.
- Helps customers manage eligible purchases over time.
6. Chase Freedom Rise
The Chase Freedom Rise is geared toward U.S. students, first-time credit seekers and consumers just beginning their credit-building journeys. Data Used: Underwriting looks at application details, traditional credit information, income and current banking relationships. A qualifying Chase savings or checking account with a minimum balance of $250 may help improve your chances of approval.
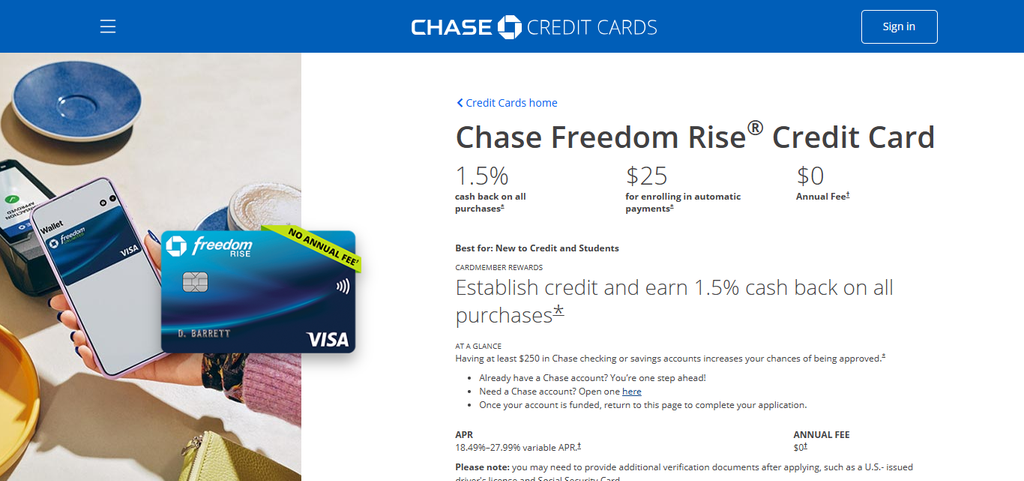
Credit Limit: Individual revolving limits are based on Chase’s approval process and can be increased with responsible account management.
Repayment Structure: Customers have minimum monthly billing cycles, payments of full balance, and automatic payments. Rewards and Benefits: Benefits include 1.5% cash back on purchases, promotional dining rewards, no annual fee and $25 automatic-payment enrollment incentive.
Rewards
- Earns cashback on eligible everyday purchases.
- Offers higher cashback on selected spending categories during promotions.
- Provides a bonus for setting up automatic payments.
- Offers rewards without an annual fee.
Benefits
- Designed for people beginning their credit journey.
- Does not require an extensive credit history.
- May improve approval chances with an eligible Chase relationship.
- Reports payment activity to major credit bureaus.
7. Upgrade OneCard
Upgrade OneCard targets U.S. consumers looking for flexible purchasing, everyday rewards and installment-style repayment. Data Used: It uses underwriting to evaluate applicant creditworthiness and financial information, but the specific variables used in transaction-level cash-flow scoring are not publicly available.
Credit Limit Depending on the customer’s eligibility and underwriting results, customers are given individually approved revolving lines of credit. Repayment Structure The Pay Now option automatically pays eligible settled purchases from linked bank accounts.
The Pay Over Time option breaks down qualifying purchases into monthly installments with fixed fees. Rewards and Benefits The Cash Rewards version offers unlimited 1.5% cash back, no annual fee, digital account management, and many payment options
Rewards
- Earns cashback on eligible purchases.
- Offers rewards through qualifying card transactions.
- Provides cashback opportunities with Pay Now purchases.
- Rewards depend on current card terms.
Benefits
- Combines payment flexibility with credit functionality.
- Offers Pay Now and Pay Over Time options.
- Provides installment-style repayment for eligible purchases.
- Helps customers manage spending through structured payments.
8. Mine
Data Used Instead of relying on traditional credit bureau or cash-flow underwriting, its platform leverages USDC funding, digital asset balances, customer verification and transaction data. Credit Limit It has no traditional revolving credit line; monthly spending limits advertized are $100,000 for Basic, $1,000,000 for Premium.
Repayment Structure Purchases are funded from available USDC balances, removing the need for traditional monthly borrowing repayments.
Rewards and Benefits Premium provides 0.5% USDC cash back on eligible spending up to $5,000 per month, Mastercard acceptance, international payments, and digital asset spending. It’s a competitor in adjacent payments, not a direct credit-underwriting competitor.
Rewards
- Offers USDC cashback on eligible card spending.
- Provides cashback based on qualifying transactions.
- Premium members receive enhanced cashback opportunities.
- Cashback is subject to monthly spending limits.
Benefits
- Supports spending through a crypto-funded payment card.
- Provides access to international card payments.
- Offers different membership tiers and spending limits.
- Supports digital asset-based payment management.
9. Deserve
Focus on underserved students, international students, young professionals and consumers with limited US credit histories. Data Used: Its alternative underwriting took into account financial documents, education, employment, income, US bank account balances and proprietary credit scoring algorithms.
Credit Limit: Prior EDU card programs offered limits as high as $5,000, depending on individual underwriting decisions. Repayment Structure: The credit cards had the usual monthly billing, minimum payment requirements, and repayment of the outstanding balance
Rewards and Benefits This used to be 1% cash back, no annual fee, reporting to the credit bureaus and easy applications for eligible international students. However, Deserve is not currently accepting new applicants for its credit card, so it is more of a historical benchmark.
Rewards
- Historical products offered cashback on eligible purchases.
- Certain cards provided rewards for everyday spending.
- Rewards varied across individual card programs.
- Historical offers included cashback without annual fees.
Benefits
- Previously supported applicants with limited credit history.
- Used alternative financial information in underwriting.
- Considered banking information and student documentation.
- Offered credit-building opportunities through reported payment activity.
10. Capital One Quicksilver Secured
Capital One Quicksilver Secured is a card for U.S. consumers who want to build or re-build credit and earn rewards on purchases. Data Used It underwrites against traditional credit information, application information, income, financial obligations and refundable security deposits. Credit Limit: Minimum deposit of $200 refundable required.
Credit limits are subject to individual eligibility and issuer’s terms. Repayment Structure: Cardholders are subject to monthly revolving credit billing, minimum payment obligations and scheduled payment deadlines.
Rewards & Benefits Unlimited 1.5% cash back on eligible purchases, No annual fee, Refundable security deposits, Opportunities to build your credit, Potential consideration for unsecured credit upgrades
Rewards
- Earns unlimited cashback on eligible purchases.
- Provides a flat-rate cashback structure.
- Offers rewards across multiple spending categories.
- Cashback does not require category activation.
Benefits
- Helps customers build or rebuild credit history.
- Requires a refundable security deposit.
- Offers access to Capital One account management tools.
- Reports payment activity to major credit bureaus.
Conclusion
Conclusion The best Petal Card competitors demonstrate the growing importance of alternative credit scoring in US cash flow underwriting. Firms such as Arro, Mission Lane, Chime, Varo and Upgrade offer access to credit, repayment flexibility and financial inclusion in different ways.
We can find opportunities in the market and understand the evolving consumer lending solutions by looking at their underwriting approaches , use of banking data , credit limits and customer benefits .
FAQ
Why is Petal considered a cash flow underwriting competitor?
Petal uses applicants’ banking information, income patterns, and financial behavior to evaluate creditworthiness and support responsible lending decisions.
Which companies compete with Petal in alternative credit assessment?
Arro, Mission Lane, Chime, Varo, and Upgrade offer credit-building products with varying approaches to evaluating applicants and managing credit.
How does cash flow data help credit card approvals?
Cash flow data helps lenders understand income consistency, spending habits, available funds, and potential repayment capacity beyond traditional credit histories.
Do Petal competitors offer credit cards without traditional credit histories?
Some competitors support applicants with limited credit histories through alternative assessments, secured products, or credit-building programs.
